By David Paul
Industry misconduct and risk do not respect company walls. Illicit practices move through the entire life insurance distribution channel wherever they find a gap, leaving the carriers, distributors, and licensed insurance agents they touch a little worse off. Most of all, they hurt the clients who trusted that the policy in front of them was sound.
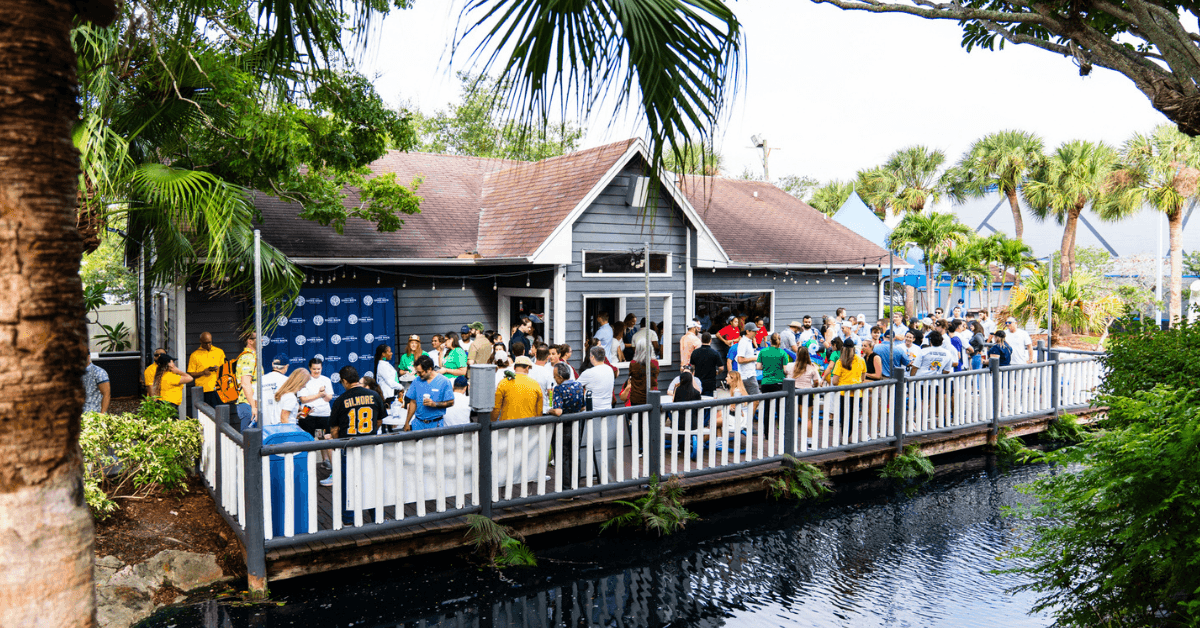
That’s why AmeriLife invited leaders from thirteen different insurance carriers to its home office for a collaborative working session with a single agenda: how the industry can mitigate the risk of fraud and misconduct together. There were no product pitches and no sales targets, just carriers and distribution at the same table, working on a problem neither side can solve alone. AmeriLife is grateful to every carrier partner who accepted the invitation, and for the trust it took to sit in the same room and speak openly about challenges this sensitive.
The carriers in the room had a name for it: an industry first – and a shared commitment to keeping bad actors out of the channel.
Why industry collaboration is the new standard
Risk mitigation is an industry-wide challenge, and it calls for industry-wide answers. That belief shaped the invitation list. Thirteen carriers, many of them competing for the same business every day, accepted without hesitation. Their response said as much as anything discussed that day, because it showed that the industry has been ready for someone to convene this conversation. Leadership in insurance distribution isn’t measured only by production. It also shows up in the willingness to fill a conference room and ask competitors and partners to find ways to solve a challenge together.
Jim Duff, SVP, Brokerage Sales, Mutual of Omaha reflects on the meeting. “Each of us has spent years fighting bad actors alone, seeing only our piece of the picture. Putting carriers and distribution in one room to compare notes was an industry first. This conversation gave us practical ideas we can act on and a network of peers we can call when something doesn’t look right.”
Effective in-person collaboration enables us to mitigate risk at the highest level, improving our return on investment and driving sustainable profit. More importantly, it helps ensure that the clients who depend on this industry receive the protection they were promised.
What is driving the rise of deceptive practices in life insurance distribution?
Life insurance distribution has changed quickly. Digital applications, faster onboarding for licensed insurance agents, and emerging technologies have opened new paths to growth, and they’ve opened a few new paths for bad actors too. The tools they use are also get smarter every year. Staying ahead means sharing what we learn faster than they can adapt. The result is a growing influx of misconduct that surfaces in the business metrics every organization watches, including placement rates, early lapses, and chargebacks.
When bad actors enter the system, they damage trust, drive up costs, and create regulatory exposure for every participant in the chain. Carriers feel it in underwriting and claims. Distributors feel it in the field. Consumers feel it through higher premiums and eroded confidence in the products meant to protect them. Every compromised application has a family behind it and that family deserves coverage it can count on.
“The true cost of illicit activity goes beyond the chargebacks,” says David Decker, SVP, National Sales Manager, Liberty Bankers Insurance Group. “It erodes the trust our clients place in us and the trust we place in one another.”
Framing risk mitigation for fraudulent practices as a shared business metric keeps the conversation grounded and practical rather than alarmist. This is a shared challenge requiring a shared response, and the cost of inaction rises every year that the industry treats misconduct as someone else’s responsibility. Every policy issued, every claim paid, and every new appointment represents a point where risk can either be managed or allowed to accumulate. Staying ahead of how new technologies reshape that risk is part of the work, too.
“New technologies are changing how bad behavior shows up, so staying ahead of it means sharing what we’re learning in real time, not after the fact,” says Jason Speigel, National Sales Manager for Corebridge Financial.
What happens when distribution and carriers work together
Here’s the heart of the issue. Distributors see what happens in the field: recruiting patterns, contracting activity, and how business is written and submitted. Carriers see what happens downstream at underwriting, issue, and claims. Each vantage point holds part of the picture, and neither holds all of it.
When distribution and carriers share intelligence, patterns emerge that neither side would spot in isolation.
The session focused on closing that gap, with participants exploring how earlier signal-sharing, clearer escalation paths, and more consistent standards could help both sides spot risk sooner. This collaboration turns two partial views into one complete understanding and that understanding is what makes proactive risk management possible. Earlier detection also means fewer clients caught in the fallout of misconduct and more confidence that the policies they purchase will hold up when they need them most.
Kyle Ingenthron, National Sales Director for American Home Life Insurance provides his insights on the collaborative meeting. “We see what comes through underwriting. Distribution sees what happens long before an application reaches us. When we share those views early, bad actors have fewer places to hide, and the licensed insurance agents doing honest work stop paying for someone else’s misconduct.”
What this meeting signals about leadership beyond the company
One meeting doesn’t redefine a company but a pattern does. AmeriLife leaders are shaping the industry well beyond their own business through external leadership roles, collaborative initiatives, and steady investment in the health of the distribution channel. That matters whether you run an agency, build a field marketing organization, or guide clients as a financial professional.
A true partner of choice strengthens the marketplace you work in, not just the business you place through it. Protecting that marketplace also protects the licensed insurance agents who do things the right way, because ethical professionals shouldn’t absorb the cost of someone else’s misconduct. Leadership in insurance distribution is measured by performance, but also by the willingness to strengthen the system everyone depends on. Carriers and distributors are finding that the fastest path to better risk outcomes runs through shared effort.
None of that happens without partners willing to show up. The carriers who joined this conversation brought candor, experience and a shared commitment to protecting clients, and AmeriLife doesn’t take that trust for granted.
What comes next for insurance industry risk management?
Nobody walked into the meeting expecting these issues would be resolved in a single afternoon. What the group did prove, though, is that carriers and distributors can sit down together, speak candidly, and find common ground regarding issues that affect everyone. That kind of trust is hard to build and easy to underestimate. The conversation started in one room, but its value depends on how widely it spreads.
Your role in that effort is bigger than it might seem. Every clean application, every question asked before a contract is signed, and every concern raised early adds up. Each one protects a client who is counting on you to get it right. The ethics of life insurance distribution is built one decision at a time, and it’s protected best when the whole industry makes those decisions together.
Key takeaways
- Deceptive activity raises costs, erodes trust, and creates potential regulatory exposure for carriers and distributors alike, so no single organization can manage it alone.
- Thirteen carriers joined AmeriLife for what they called an industry-first working session, a clear sign the industry is ready for collective action.
- Distributors see field activity and carriers see underwriting and claims. Effective risk mitigation depends on connecting the two.
- The strongest partners invest in the health of the entire distribution channel, not just their own business.